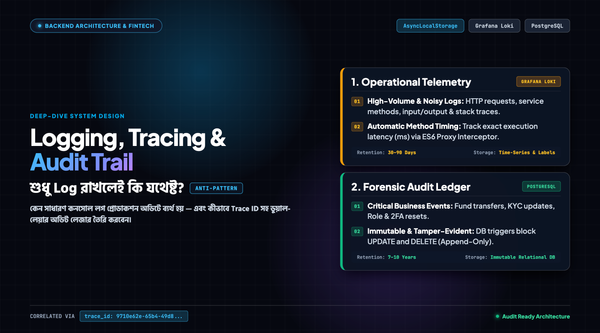
Logging, Tracing & Audit Trail: একটি Software System এ শুধু Log কি যথেষ্ট?
বর্তমানে একটি Software Product তৈরি করা আগের চেয়ে অনেক সহজ হয়ে গেছে। AI assisted development এর কারণে অনেকেই এক দুই দিনের মধ্যে একটি কার্যকর MVP তৈরি করে লঞ্চ করে ফেলেন।
বর্তমানে একটি Software Product তৈরি করা আগের চেয়ে অনেক সহজ হয়ে গেছে। AI assisted development এর কারণে অনেকেই এক দুই দিনের মধ্যে একটি কার্যকর MVP তৈরি করে লঞ্চ করে ফেলেন।
আপনি যদি কোনো Authentication Service তৈরি করেন এবং সেখানে Access Token ও Refresh Token ভিত্তিক সেশন সিস্টেম ব্যবহার করে থাকেন, যেখানে টোকেন expire হলে তা রিনিউ করার
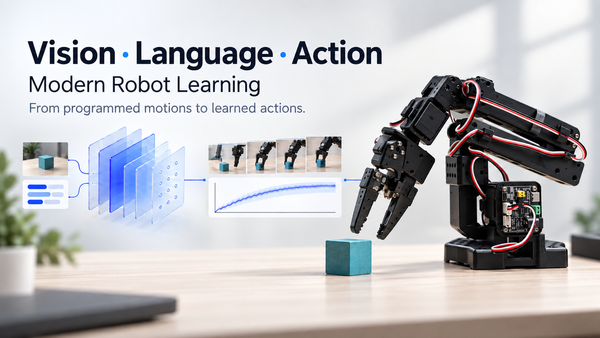
VLA evolution and architectures, followed by hands-on robot assembly, data collection, training, and inference. Authors: Mahtab Newaz | Spectrum Software & Consulting (Pvt.) Ltd. AI/ML Team Published: 21st Sept, 2026 Reading Time: ~60 min Tags: Physical AI VLA Embodied AI Robotics Imitation Learning How do foundation models turn visual observations
যেমন ধরুন—ইভেন্টের টিকিট বুকিং, ফ্ল্যাশ সেল কিংবা কোনো ভাইরাল ক্যাম্পেইনে প্রতি সেকেন্ডে হাজার হাজার ইউজার একযোগে পারচেজ
A successful ECL implementation cannot depend on scattered spreadsheets. The framework requires regular data collection, model execution, scenario analysis, calculation, approval, reporting, and auditability. That means banks need a technology architecture that can support the full ECL lifecycle. Why Excel is not enough Excel may be useful during early analysis
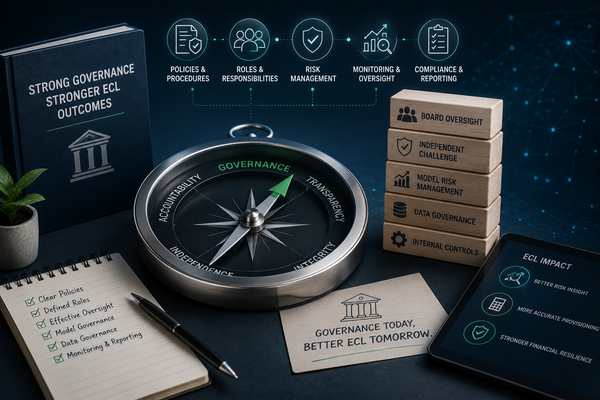
Many people think ECL is only about provisioning. That is only part of the story. Expected Credit Loss will affect how banks approve loans, monitor portfolios, price risk, plan capital, report to boards, and communicate with regulators. In other words, ECL is not only an accounting requirement. It is a
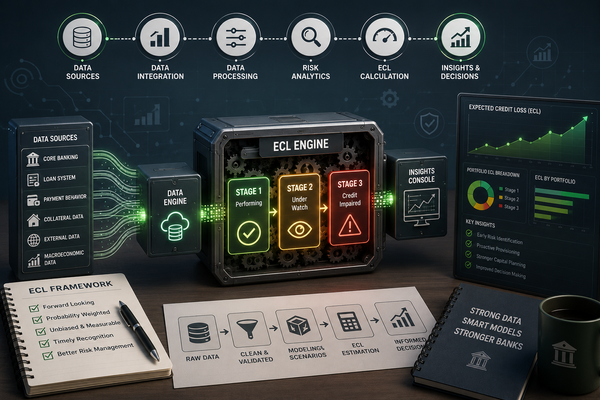
Most ECL projects do not fail because people misunderstand IFRS 9. They fail because the required data is missing, scattered, inconsistent, or unreliable. Expected Credit Loss depends on models. Models depend on data. If the data is weak, the ECL output will also be weak. That is why data readiness
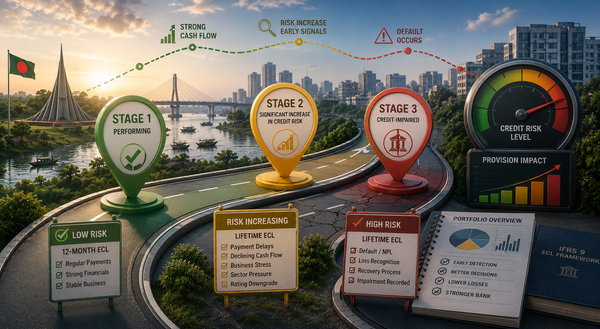
Every loan has a life story. It starts with approval, disbursement, repayment, monitoring, and eventually closure. But during that journey, the credit quality of the borrower may change. A borrower may begin as financially strong. Later, cash flow may weaken. Eventually, the borrower may become unable to repay. IFRS 9
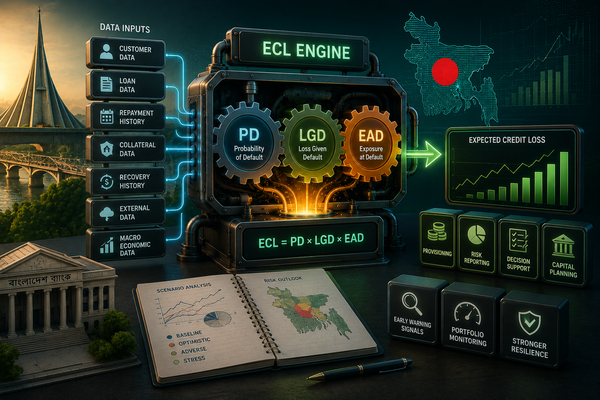
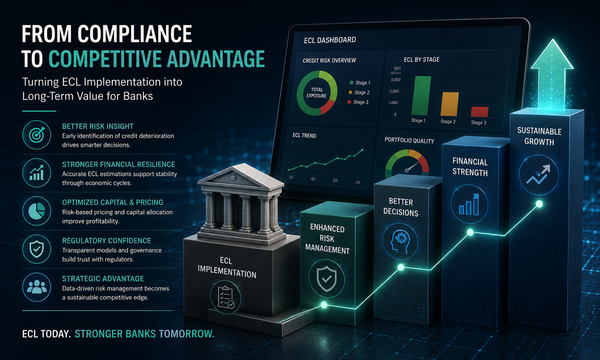
When people hear “Expected Credit Loss,” they often think of an accounting calculation. But in practice, ECL is much more than a formula. It is a risk prediction framework that brings together data, models, assumptions, economic forecasts, and governance controls to estimate how much loss a bank may face in
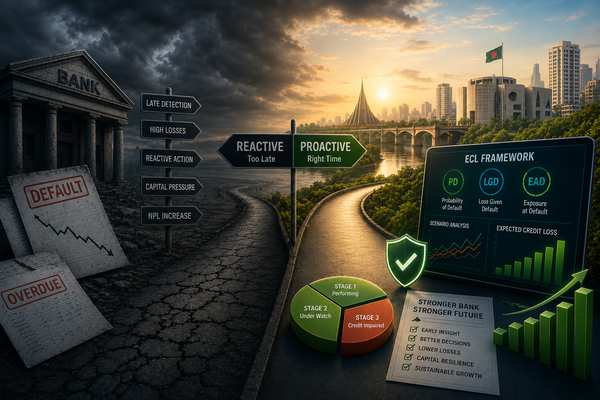
A borrower rarely becomes risky overnight. A trading company may continue paying installments on time, while its sales are already declining. A manufacturing client may still look healthy in the core banking system, while raw material prices, exchange rate pressure, or falling export orders are silently weakening its cash flow.
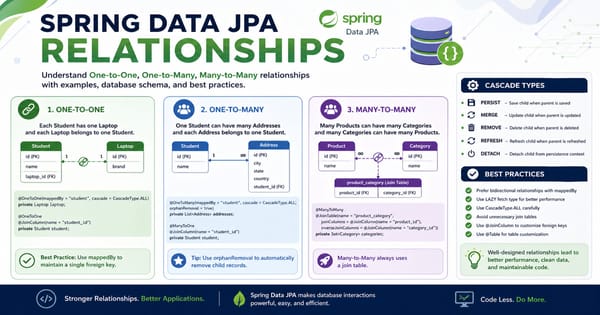
Master @OneToOne, @OneToMany, and @ManyToMany with Real Code Examples What You Will Learn This guide covers all types of JPA entity relationships — @OneToOne, @OneToMany, @ManyToMany — with uni-directional and bi-directional variants, cascade types, fetch strategies, and the @Table annotation. Each section includes annotated code examples and the resulting database schema, so
A walkthrough of every system, switch, and compliance checkpoint a single remittance dollar passes through on its way from a sender abroad to a beneficiary in Bangladesh.